 Malunggay Compass
- What it actually costs to start
- Fund it in the right order
- Where the money comes from
- Agri-agra: how banks count you
- Cooperatives & clustering
- Buyer advances & contract growing
- Working capital: the real constraint
- Risk transfer & buffers
- Public programs & grants
- A one-page financing plan
- Seven ways it goes wrong
Loan amounts, rates, fees and amortisations below are illustrative arithmetic on plausible planning numbers — not offers, quotes or financial advice. Philippine agri lending terms depend on the institution, the collateral, the program cycle and your own records, and they change. Confirm every figure with the lender, your Municipal Agriculture Office, and your cooperative before signing anything.
1. What it actually costs to start
Moringa has a reputation as a cheap crop, and for household production it is. Commercial production is not cheap — it is staged. The money problem is rarely the total: it is that the costs arrive before the revenue does.
The sample budgets lay out the line items in full. What matters for financing is their shape over time:
| Stage | What you are buying | When it is spent | When it earns |
|---|---|---|---|
| Establishment | Land preparation, planting material, compost and lime, the first fertilisation, irrigation setup, weed control | Months 0–3, front-loaded and almost entirely cash | Months 3–6 (first light harvests) |
| Build-out | The second and third blocks, nursery expansion, tools, fencing, windbreak species, drainage works | Months 6–18 | Months 12–24, if the first block is already selling |
| Processing | Drying shed or mechanical dryer, mill, tables, sealing equipment, packaging, storage racks | Lumpy: one purchase, one decision | Immediately, by converting lower-value fresh leaf into higher-value powder |
| Compliance & market | Business registration, FDA licence to operate, product registration, lab tests, labels, samples | Before you can sell formally at all | Months later — this is the slowest payback stage |
| Working capital | Labour for harvests, drying, milling and delivery, plus the gap between delivering and being paid | Continuously, every single cycle | Continuously — and it is what actually runs out |
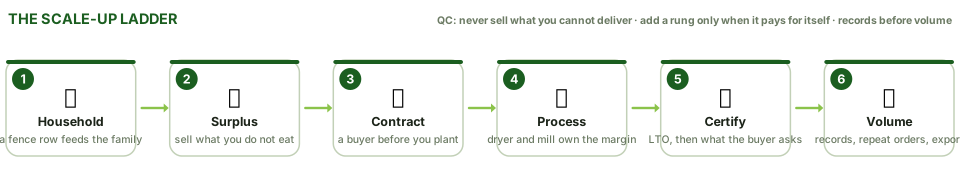
2. Fund it in the right order
Every rule in this chapter collapses into one sequencing discipline: spend money on the constraint, not on the dream. The constraint is whatever is currently capping your output — water, drying capacity, labour at harvest, or a buyer.
Prove the plant
Before any loan: a fence row, a backyard block, or a quarter hectare that you planted with your own cash. You need to know your own germination rate, your own first-cut timing, and your own soil's behaviour — all of which are free to learn here, and expensive to learn by borrowing.
Prove the buyer
One written order or one standing weekly delivery changes a plan from a projection into a schedule. Lenders and cooperatives both respond to paper. See the buyer toolkit.
Prove the unit cost
Weigh a cut, time the stripping, count the man-days, log the drying ratio. A farm that knows it costs ₱X to produce a kilo can borrow for a specific improvement with a defensible repayment plan.
Then borrow — for the constraint
Only now is a loan for irrigation, a dryer or a nursery rational, because you can name what it will produce and when it will pay.
The classic failure is inverted: borrow first, plant a large block, buy a dryer before there is volume, then look for a buyer to service the repayment. Every later decision is then made under time pressure, which is exactly how growers accept bad prices, sell immature product, and take the first contract offered — including the one in section 11.
3. Where the money comes from
Philippine growers fund moringa from nine sources, in descending order of how often they actually work for a new enterprise:
| Source | Typical use | Cost / terms | The catch |
|---|---|---|---|
| Own cash flow | Everything, if you grow at the pace of section 2 | Zero interest | Slow. Usually the correct answer anyway. |
| Family and relatives | Land prep, seedlings, a first drying shed | Often informal or interest-free | Family terms are implicit and can sour faster than a bank's. Put the amount and the plan in writing regardless. |
| Cooperative / association | Shared dryer, shared hauling, aggregated volume | Low fees; membership share capital | Governance. Read the bylaws, know the officers, and never lend your receipts to the treasurer of a group you cannot audit. See section 5. |
| Bank agri / aquaculture loan | Irrigation, dryer, mill, transport, land lease | Secured, often requiring collateral or a co-maker | Documentation. Banks approve records, not plants — see section 12. |
| Agri-agra-mandated lending | Same as above, where the bank counts your loan toward its allocation | Potentially the most favourable formal rate available | Eligibility is a question for the bank: ask whether your loan qualifies as agricultural or aquaculture lending. See section 4. |
| Buyer advance / contract growing | Inputs against a committed harvest | No interest — but the price is set by the agreement | You have converted a loan into a price commitment. Only worth it if the committed price is a fair one. See section 6. |
| Supplier credit | Seed, fertiliser, trays, packaging bought on terms | Implicit interest in the price | Price it: "₱X now or ₱Y in 60 days" is a rate, and it is usually high. |
| Government programs & grants | Inputs, seedlings, equipment, training, facilities | Subsidised or in-kind; competitive and cyclical | Timing is not yours. Never build a plan whose feasibility depends on an application succeeding. See section 9. |
| Informal lenders | Emergency cash | Quoted per month, and it compounds | A rate that sounds small per month is a multiple per year. It is the most reliable way to lose a farm that is merely having a bad quarter. |
4. Agri-agra: how banks count you
Philippine banking law obliges banks to set aside a share of their loanable funds for agriculture and fisheries lending, and to allocate a portion of that to agrarian reform beneficiaries. The current framework is the Agriculture, Fisheries and Rural Development Financing Enhancement Act (Republic Act 11901, 2022), which replaced the earlier Agri-Agra Reform Credit Act and shifted the emphasis toward actual agri-fishery lending rather than compliance by other means.
What this means in practical terms for a moringa grower:
- There is institutional appetite for qualifying agricultural loans that most borrowers never ask about. It costs nothing to ask.
- The question to ask is specific. Not "do you fund farming?" but "does a moringa leaf-production and drying loan qualify as agricultural or aquaculture lending under your agri-agra program, and what documents does that program require?"
- Banks still price risk, not policy. A program allocation does not remove the collateral, co-maker or cash-flow requirements — it changes which window your application goes through.
- Land Bank and DBP are the two most likely places to start, alongside rural banks and cooperative banks with agricultural portfolios and the Agricultural Credit Policy Council (ACPC) program pipeline.
1) Does my enterprise qualify as an agricultural loan? 2) What is the current rate and term for that product? 3) What collateral or guarantee do you require, and do you accept a co-maker or a cooperative guarantee? 4) What records must I show? Write down the answers and compare across at least three lenders before you decide anything.
5. Cooperatives & clustering
For a crop grown mostly on small parcels, the cooperative is the single most powerful financing structure available — because it converts many small, unbankable operations into one larger, financeable one.
What a cooperative does well
- Aggregates volume to a size an institutional buyer or feed mill will actually talk to.
- Shares lumpy assets — one dryer, one mill, one delivery vehicle serving twenty members instead of one member owning all three.
- Provides a guarantee that a member's own collateral cannot, opening formal credit to growers with small holdings.
- Standardises practice through shared training, shared seed sources, and a common quality bar — which is what buyers are really buying.
- Reaches programs that are awarded to organisations rather than individuals, including many DA and LGU facilities and training grants.
What it does badly
- Governance risk. A cooperative's books are only as good as its treasurer and its audit committee.
- Slow decisions. Consensus costs weeks, and harvests do not wait.
- Free-riding. One member delivering wet, stemmy leaf drags down the batch price for everyone, unless the group grades at the receiving point.
- Debt contagion. A joint loan is joint: understand who is liable, and for how much, before you sign the resolution.
If you join or form one, insist on three things from the start: graded receiving (paid by quality, not by relationship), written minutes for every financial decision, and a published unit cost for every shared service — drying per kilo, milling per kilo, hauling per trip.
6. Buyer advances & contract growing
An advance against a committed harvest is the most common form of moringa financing in practice, and it is neither good nor bad on its own. It is a trade: the buyer supplies cash now and takes price certainty later.
| Structure | Who carries the risk | Fair when… | Dangerous when… |
|---|---|---|---|
| Inputs in kind (seedlings, fertiliser, trays) | Buyer carries input-cost risk | You need inputs now and the quantity is small; the price mechanism is left open | In-kind inputs are priced well above the local market and counted against your harvest |
| Cash advance repaid in product | You carry the production risk; buyer carries the price risk | The conversion rate (kilos per peso) is written down and is close to the prevailing farmgate | The advance is unquantified and settles "at prevailing price" — a blank cheque in the buyer's handwriting |
| Contract growing with fixed price | Buyer takes price risk, you take volume risk | The fixed price covers your measured cost plus a margin, and quantity tolerances are realistic | Payment is on delivery of the full committed volume, so one bad month wipes the whole agreement |
| Speculative planting, no buyer | You carry everything | Never for a commercial block | Always — this is not financing, it is a hope with a labour bill |
An advance is only a good deal if you would have signed the price clause independently. The test is simple: if the price in the contract were today's farmgate price and you owed nothing, would you still sell to this buyer? If the answer is no, the advance is not financing — it is a discount you are paying for cash you should have obtained elsewhere.
7. Working capital: the real constraint
A profitable farm can still fail, because profit is a number on paper and cash is what pays the harvester on Saturday.
Moringa's cash cycle has one structural problem: your costs are paid in full at harvest, and your money arrives later. Harvest labour, stripping, fuel, drying, milling and packaging all happen up front. Payment follows — and in the fresh market it may follow quickly, while in formal and institutional channels it may take a month or longer.
| Channel | When you spend | When you are paid | Gap to finance |
|---|---|---|---|
| Palengke / cash selling | Harvest day | Same day | Days — financeable from petty cash |
| Restaurants & canteens | Harvest day | On invoice, typically weekly to monthly | 2–4 weeks |
| Institutional / LGU supply | Harvest day | On government payment cycles, often 30–60 days or more | 1–3 months. This is the one that empties a small farm's cash box. |
| Powder processors | Harvest day, plus drying and milling weeks | On delivery, or per agreement | 2–6 weeks, plus inventory sitting in finished goods |
| Export | Harvest, processing, packing, freight | On terms after shipment | Months. See the export playbook for how payment terms work. |
The three pots of money
Separate them physically — different accounts, different envelopes, different notebooks. Growers who merge them cannot tell profit from survival:
- The operating pot. Harvest, drying, milling, transport, packaging. Refilled by sales. If it is empty, you cannot harvest, regardless of how good the crop is.
- The replacement pot. Reserves for wear: blades, seals, tarpaulins, drying trays, the eventual dryer repair. Small, boring, and the reason equipment lasts.
- The shock pot. Your own storm and failed-flush fund, sized to roughly one harvest cycle of costs. It is the cheapest insurance you will ever buy — see enterprise resilience.
Work the arithmetic once with your own numbers. It usually produces a smaller number than growers fear and a larger one than they expect — and it is the single most useful figure to have ready when a lender asks about repayment capacity.
8. Risk transfer & buffers
Financing and risk are the same conversation from two directions: the cheapest loan is worthless if one season can erase it.
🛡️ Insurance
Crop insurance delivered largely through PCIC covers high-value crops, and moringa sits inside that category. Enrolment in the RSBSA is the usual gate, premium rates depend on the crop and program, and documented damage is what gets a claim paid. The mechanics are in Climate Resilience.
🌱 Self-insurance
A diversification buffer: staggered planting so not every block is at the same growth stage, a processing buffer so a distressed flush becomes powder instead of waste, and a shock pot sized to a full harvest cycle.
🤝 Pooling
A cooperative can carry risk a household cannot: shared drying means one member's wet harvest is not a total loss, and shared volume means a failed block does not cost a contract.
📝 Documentation
The cheapest risk tool is a dated photograph, a harvest log and a delivery receipt. They turn a loss into a claim, a dispute into a record, and a guess into a decision. See lot coding and traceability.
9. Public programs & grants
Government support for a crop like moringa arrives mostly as inputs, equipment, training and facilities rather than as cash, and mostly through these doors:
| Door | What tends to come through it | Where to ask |
|---|---|---|
| DA High-Value Crops Development Program (HVCDP) | Planting material, small tools, postharvest and processing facilities, training and market linkage for high-value crops | Provincial / municipal agriculture office; see Industry & Policy |
| LGU programs | Seedlings, demonstration plots, feeding-program supply contracts, shared facilities | Municipal or city agriculture office |
| ACPC-linked credit programs | Concessional lending windows channelled through banks and cooperatives, sometimes with guarantee cover | Land Bank, DBP, rural banks, cooperatives |
| DOST / PCAARRD | Technology transfer, product development, testing support, equipment for processing upgrades | Regional DOST office, state universities |
| DTI | Product branding, labelling, packaging, trade fair and export-market entry support | Provincial DTI office; align with export |
| Cooperatives development programs | Facilities and financing for CDA-registered groups | CDA regional office, cooperative federation |
Programs fund requirements, not ideas: land you already hold, a functioning block you already manage, records you already keep, and a buyer you can name. Prepare those first and applications become a formality. Apply first and you will be told to come back when you have them.
10. A one-page financing plan
Anything longer than one page will not be read by the person you are asking. Write this, in this order, and keep it current:
The enterprise in one sentence
"A 1-hectare leaf block producing dried powder for one institutional buyer, plus a nursery selling 5,000 seedlings a year." Specific, sized, and named.
What exists today
Area planted, age of the blocks, trees or hedges established, equipment owned, records kept, buyers served. Physical facts only.
Measured unit economics
Your own yield per cut, your own fresh-to-dry ratio, your own labour cost per kilo, your own selling price. Mark anything not yet measured as an assumption.
The ask, tied to the constraint
"₱X for a covered drying shed, which raises sellable powder from A to B kilos per month by removing mould losses in the wet season." One number, one purpose.
Repayment or payback
If it is a loan: when and from what cash flow the instalment is paid, in the worst month as well as the average. If it is a grant: what the facility produces and who else benefits.
The downside case
What happens if the wet season is long, a storm lands, or the buyer delays payment two months. Lenders trust a borrower who has already imagined the bad quarter.
Evidence pack
Pictures of the farm, sample records, delivery receipts, a quotation for the equipment, and a letter from a buyer if you have one.
11. Seven ways it goes wrong
| Mistake | What it looks like | The correction |
|---|---|---|
| Borrowing before measuring | A loan sized from a chapter's indicative yield rather than your own block | Measure one full cycle first. See section 2. |
| Buying the dryer first | Equipment idling while the planting is still being established | Buy capacity at 60–70% utilisation, not 20%. See drying. |
| Financing the whole ladder | Planting, processing and certification all funded from one borrowing decision | Fund one rung; let it repay the next. |
| Ignoring the collection gap | A profitable institutional contract that cannot be delivered to because the operating pot is empty | Size the cushion in section 7 before accepting the contract. |
| Unpriced advances | An input advance settling "at prevailing price" on delivery day | Write the conversion rate into the agreement. |
| Merging the pots | Household money and farm money in one wallet | Separate them physically, even if only by envelope. |
| No paperwork | Years of production with nothing a lender, insurer or auditor would accept | Start the log today; it costs nothing and it is the only asset that compounds. See traceability. |
12. Records lenders actually require
Banks and cooperatives do not underwrite enthusiasm. They underwrite evidence, and the same evidence supports your insurance claim, your compliance audit, and your own decisions:
- Land: title, tax declaration, lease agreement, or a barangay certification of use.
- Production: planting dates, block areas, cut dates, harvest weights, drying ratios, finished product weights.
- Sales: delivery receipts, invoices, purchase orders, or a written supply agreement.
- Costs: labour days, input purchases with receipts, transport and packaging costs.
- Identity and standing: business or registration documents, RSBSA enrolment, permits, and — where relevant — certification.
The log you keep for a lender is the same log that supports an insurance claim after a storm, proves a lot's history to a buyer, and tells you which block actually makes money. There is no cheaper infrastructure on a farm — and no more expensive omission.